Family Businesses in Transition: Strategic Confidence Despite Structural Challenges
The KPMG Global Family Business Report 2026 shows that, despite geopolitical uncertainties and technological upheavals, family businesses worldwide are looking to the future with confidence. Swiss companies rank well above the global average in AI implementation and risk management—but face important decisions regarding governance and succession.


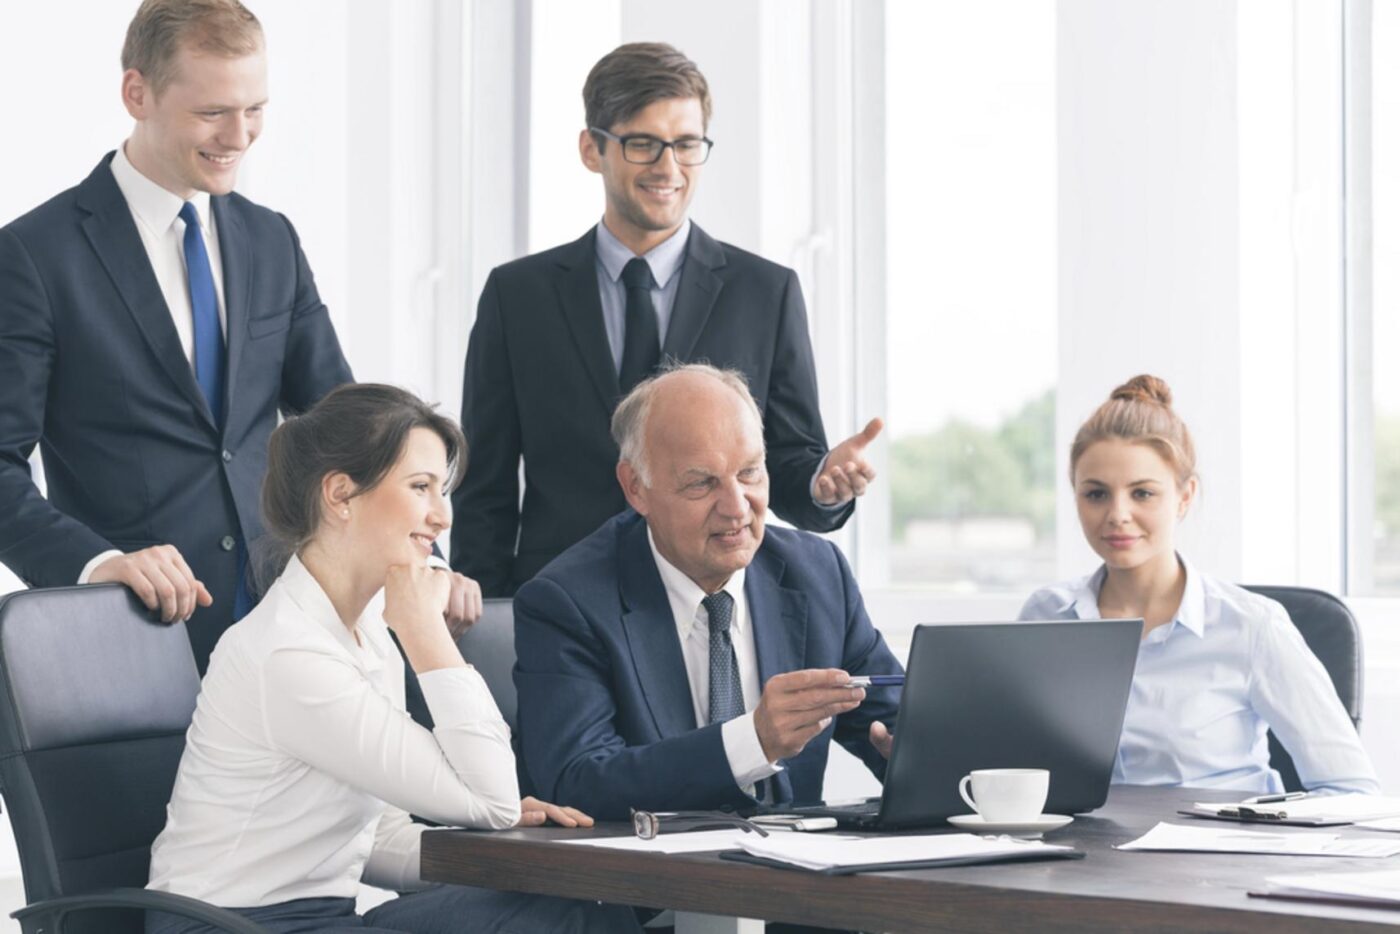
Family businesses worldwide demonstrate a high degree of strategic clarity: 83 percent are pursuing a clear growth strategy, even though 59 percent expect growth to become more difficult in the future. These are key findings from the KPMG Global Family Business Report 2026, for which a total of 1,927 owners, board members, and executives of family businesses in 41 countries were surveyed in collaboration with the research institute Meridian West. The Swiss analysis is based on 30 valid responses.
Swiss Family-Owned Businesses Are Well-Positioned
The results from Switzerland are better than the global average in several key areas. Ninety percent of Swiss respondents have a clear growth strategy—seven percentage points more than the global average. At the same time, they cite geopolitical trade and tariff risks as short- and long-term challenges significantly more often than their international counterparts.
Swiss family-owned businesses are particularly progressive when it comes to using AI: 70 percent are already actively using artificial intelligence, and 43 percent have already implemented AI broadly across various business areas—compared to just 20 percent globally. Switzerland also leads the way in risk management: 50 percent of the Swiss companies surveyed have a comprehensive enterprise risk management framework, compared with a global average of 33 percent.
Shared Values as a Key Success Factor
Globally, shared values and corporate purpose (89 percent), family reputation (87 percent), and a long-term approach to capital (83 percent) are among the most important value drivers for family businesses. The figures from Switzerland confirm this picture: 90 percent rate shared values as an important value driver, 87 percent cite family reputation, and 80 percent point to the long-term approach to capital.
These strengths continue to make the family business model a relevant competitive advantage—even though structural change is unstoppable.
Structural Change Toward Professional Management Structures
A key finding of the report: The percentage of companies that describe themselves as family-run is expected to decline worldwide from 49 percent to 12 percent by 2035. Professional management structures and board models are gaining in importance. Swiss family businesses also anticipate this shift—though the role of family members in leadership positions is significantly more pronounced here than the global average. While only 24 percent worldwide expect family members to hold the majority of leadership positions in the future, this figure stands at 43 percent in the Swiss sample.
AI Adoption Is Outpacing Governance
The rapid spread of artificial intelligence presents a new challenge for family-owned businesses: its adoption is outpacing the development of governance structures. Globally, 38 percent of all companies surveyed do not yet have a governance framework in place for AI use. In Switzerland, this figure is significantly lower at 23 percent; 77 percent report that they have already established governance structures or are actively developing them. Nevertheless, the study identifies this gap as one of the key challenges of the coming years.
Key Tasks for the Future
The report makes it clear that family businesses—including those in Switzerland—face important decisions: governance structures must be further developed, AI must be managed responsibly, the next generation must be prepared for future leadership and ownership roles, and structural change must be actively shaped. Strategic confidence is present—the decisive factor will be how consistently the necessary transformations are implemented.
Source: www.kpmg.com